Roof Claim Denied or Underpaid in PA? Here's What to Do Next
A denial letter or a payout that doesn't come close to covering the repair is one of the most frustrating moments in a storm-damage claim. It's not always the end of the road. Here's why roof insurance claims get denied or underpaid in Pennsylvania, and the real, honest options homeowners have from there.
Common Reasons a PA Roof Claim Gets Denied or Underpaid
- Classified as wear and tear, not storm damage. Insurers only cover sudden, documented events — not a roof that was already near the end of its life.
- Damage below your deductible. If the documented loss doesn't exceed your deductible ($250, $500, $1,000, or 1% of dwelling coverage, depending on your policy), there may be nothing left for the insurer to pay.
- Thin or missing documentation. A claim built on a few phone photos gives an adjuster less to work with than a HAAG-certified inspection report.
- Missed scope in the adjuster's estimate. Extra layers, code-required upgrades, or decking damage that's only visible once the roof is opened up are easy for a fast-moving adjuster to miss.
- Filed too late. Pennsylvania policies generally require filing within one to two years of the date of loss.
Step 1: Get the Adjuster's Written Estimate and Denial Letter
Every next step starts here. The denial letter or estimate should state the specific reason for the decision. Without that in writing, there's nothing concrete to respond to — so this is the first thing to request if you don't already have it.
Step 2: Request a Second Inspection or Re-Inspection
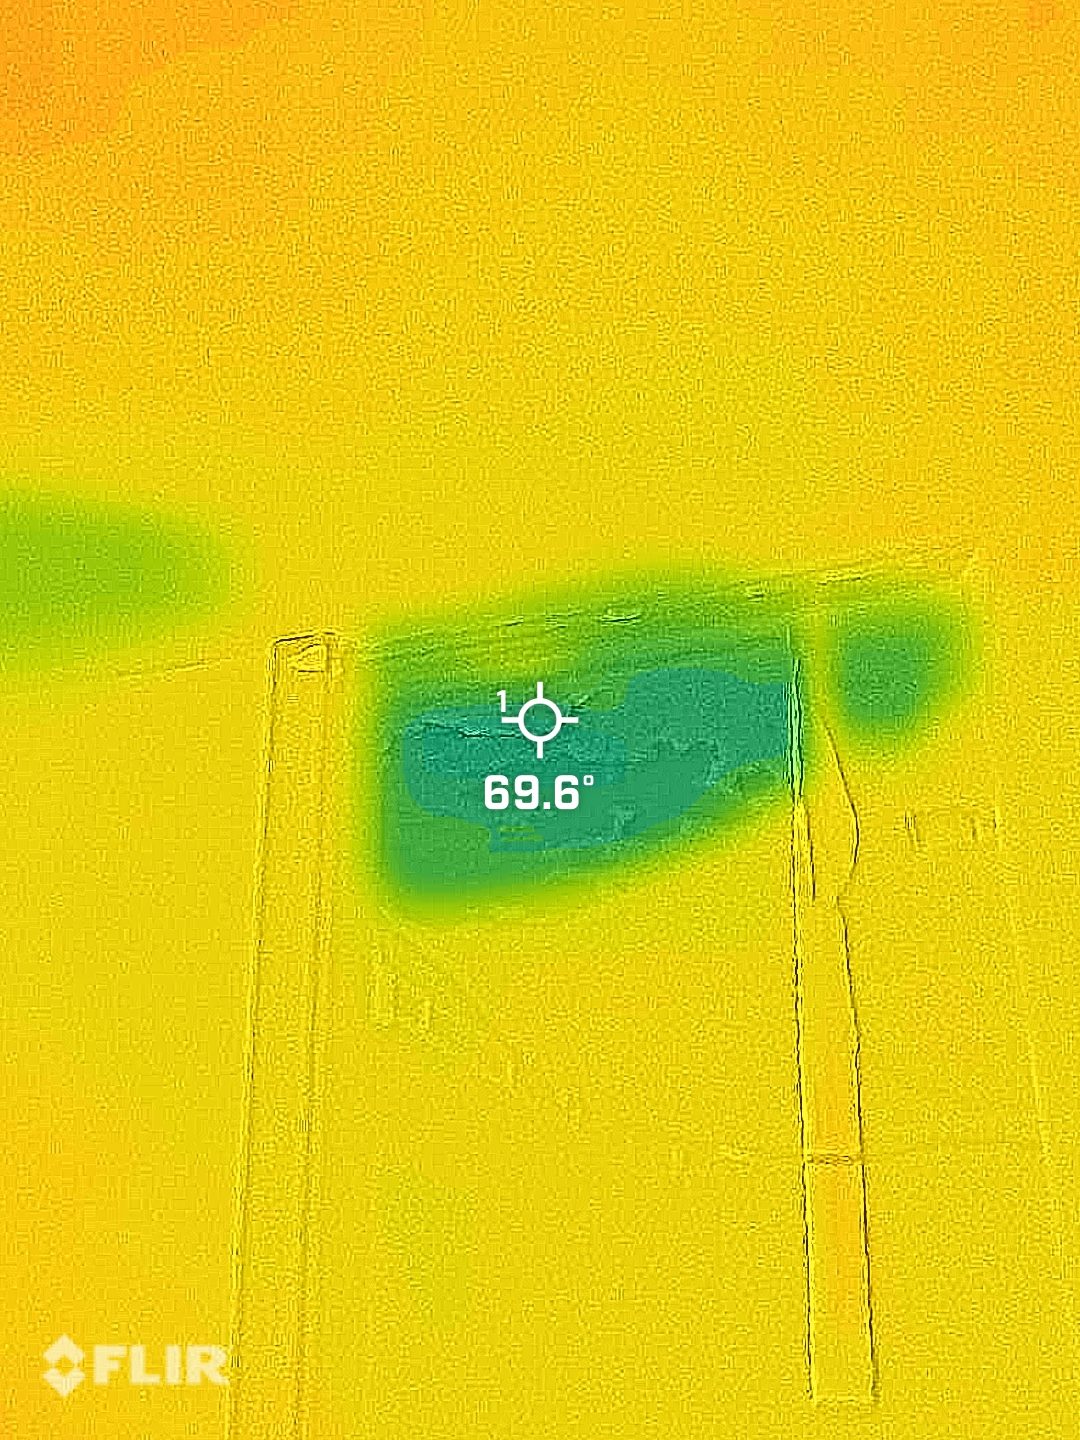
If you believe the adjuster missed damage, most carriers will schedule a re-inspection when you present new documentation. We provide a free, HAAG-certified inspection and written report specifically for this — photographing every impact point, exposed mat, and damaged accessory so the follow-up review has something concrete to work from.
Step 3: File a Supplement for Missed Scope
If the claim wasn't denied outright but the payout is short, a supplement is usually the right tool — a formal, itemized request asking the carrier to add specific, documented scope to the estimate. We write these in Xactimate, the same software most carriers use, and reconcile our scope against the adjuster's line by line so the request is specific, not just "the number feels low."
Supplement vs. dispute
A supplement corrects a scope that's missing real items. It's a normal part of many roof claims, and it's different from disputing a full denial — which is a separate process.
When to Consider a Public Adjuster, Appraisal, or the PA Insurance Department
We are a roofing and restoration contractor — not a public adjuster or attorney, and we don't negotiate your settlement on your behalf. If your claim is fully denied, or you believe the payout is far below what's needed to repair your home even after a supplement, Pennsylvania homeowners have other options worth knowing about:
- Your policy's appraisal clause. Most homeowners policies include a formal appraisal process for resolving a disputed dollar amount.
- A licensed Pennsylvania public adjuster. Public adjusters are licensed specifically to represent homeowners in negotiating a claim settlement.
- The Pennsylvania Insurance Department. Homeowners can file a complaint if they believe a claim was handled in bad faith or mishandled.
Whichever path fits your situation, we're glad to keep providing the documentation, photos, and written scope that any of those routes will need.
What The Helping Co. Does — and Doesn't Do
To be clear about where we fit in: we document the damage, meet your adjuster on-site, reconcile the repair scope line by line, and file supplements for scope the estimate missed. We don't negotiate your settlement, and we aren't public adjusters or attorneys. Our job is to make sure the physical damage to your home is fully and accurately documented — so whichever path you take next, you're doing it with real evidence behind you.
Claim Denied or the Number Feels Wrong?
Get a free, HAAG-certified second opinion on the damage before you decide what to do next.